
Go Program Way2Go Card
- Rating
- 3.5
- Downloads
- 1.00M
- Content Rating
- Everyone
Go Program Way2Go Card - Screenshots
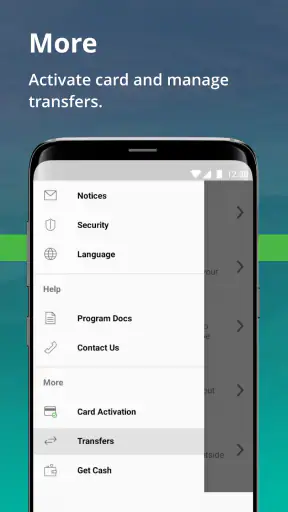
Pros
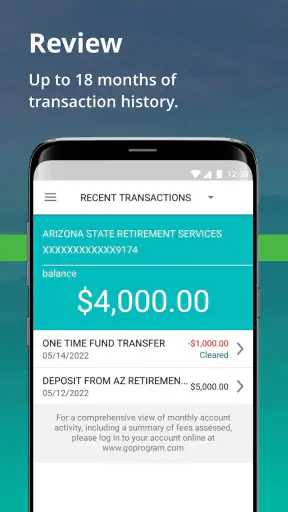
- Quickly check your Way2Go Card balance and recent transactions.
- Convenient access to card details while traveling or shopping.
- Helps monitor deposits and spending without calling customer service.
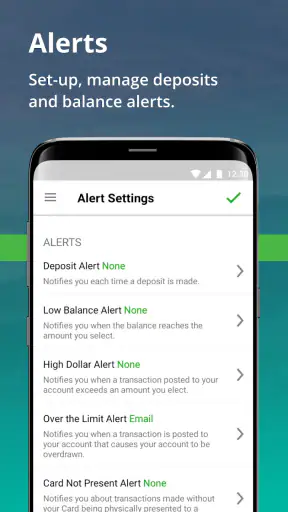
- Useful alerts can make it easier to track account activity.
- Free app download for eligible Way2Go Card users.
Cons
- Only works with participating Way2Go Card programs.
- Some features may vary depending on your state or card issuer.
- Login or verification issues can prevent access to account information.
- Transaction updates may not appear instantly after card activity.
- Requires an internet connection for most account functions.
Go Program Way2Go Card - Description
- App Name
- Go Program Way2Go Card
- Package Name
- com.xerox.epc.way2go
- Developer
- Conduent Incorporated
- Category
- Finance
- Last Updated
- Aug 14, 2015
- Version
- 3.3.5
When money arrives on a Way2Go Card, the most useful thing I want is not a complicated budgeting system. I want a quick answer to a simple question: how much can I spend, and what has already come out of the account? Go Program Way2Go Card is built around that practical need. It is a free finance app from Conduent Incorporated that lets me monitor the balance and transaction activity connected with the card.
That narrow purpose is both its strength and its limitation. During my first look, the app felt more like a dedicated account window than a full personal-finance tool. I would not choose it to plan investments, manage several bank accounts, or replace a detailed budgeting app. I would choose it when the Way2Go Card is already part of my everyday finances and I need a convenient way to keep an eye on it.
The app has been available since August 14, 2015, and its current version is 3.3.5. It is listed for Everyone, costs nothing to download, and requires operating system version 10 or later. With more than a million installs, roughly 58 thousand ratings, and an average score of 3.5, it clearly serves a sizable group while also showing that the experience is not universally smooth.
What the first week feels like
The first-week appeal is easy to understand. Instead of searching for a browser page or keeping a mental estimate of recent card use, I can open one dedicated place to check the available balance and review activity. That makes the app especially useful after a payment, withdrawal, or other card transaction when I want to make sure my remaining funds look right.
I found the focused design more reassuring than a general banking app would be in this particular situation. A normal bank application often surrounds a balance with transfers, savings tools, credit products, alerts, and promotional material. Those options can be valuable, but they also make a quick check feel heavier. Way2Go Card keeps my attention on the card account itself.
A realistic everyday example is grocery shopping near the end of a payment period. Before leaving home, I can check the available amount rather than rely on an old note or memory. Afterward, I can look at the transaction activity to confirm that the purchase appears as expected. That small routine can prevent an embarrassing declined payment and makes it easier to notice activity that deserves a closer look.
The first week is also when I would decide whether the app is dependable enough to become a habit. A balance-checking tool has to be judged differently from a social app or a game: speed, clarity, and consistency matter more than visual excitement. If opening it becomes a predictable two-minute check, it has already earned some value. If I have to repeatedly work around confusing screens or wait for information to make sense, the novelty disappears quickly.
Useful for checking, not for replacing a financial plan
One important distinction is that the app shows me the state of the Way2Go Card, but it does not become my entire financial picture. I still need another method for rent, bills, cash held elsewhere, and longer-term planning. Someone who expects category budgets, spending charts, bill scheduling, or a combined view of several accounts may feel restricted.
That is not necessarily a flaw in the app’s intended role. A dedicated card companion can be better than an oversized financial dashboard when the only recurring task is checking available funds and recent movement. The trade-off is clear: less distraction and a simpler purpose, but fewer tools for making broader decisions.
I would also treat the transaction list as a monitoring aid rather than a substitute for careful record keeping. When a purchase is unfamiliar, the useful workflow is to compare the entry with the receipt, remember when the card was used, and investigate through the appropriate support channel if something still looks wrong. The app can help me spot a question; it does not remove the need to resolve that question.
The small habits that make it worthwhile
The strongest use case is a short routine rather than constant checking. I would open the app before a larger purchase, after several small purchases have accumulated, and whenever the balance seems different from my own estimate. Those moments turn the app into a practical guardrail instead of another notification source competing for attention.
A less obvious benefit is the ability to use transaction activity as a memory aid. Small purchases are easy to forget, especially when several happen in one day. Looking back at the list can reveal why the available balance changed and can help me identify spending patterns that are otherwise invisible. I do not need a sophisticated chart to notice that frequent minor purchases have added up.
Another useful habit is checking before making a commitment, not only after a transaction. If I know a payment is coming, a pre-purchase balance check gives me a more realistic picture of what is available. This is particularly helpful when I have not used the card recently or when several pending or recent transactions make my mental calculation unreliable.
Whether it still earns a place after the first month
After the first month, the question changes from “Is this convenient?” to “Do I still need it installed?” For me, the answer depends on how often the Way2Go Card is used and how important immediate visibility is. If the card receives regular funds or covers everyday expenses, the app can become a quiet, recurring utility. If I use the card only occasionally, a browser-based alternative may be enough.
The month-to-month value comes from repetition. Each balance check is brief, but the accumulated value is the confidence that I know what is available before spending. That is not glamorous, yet it is exactly the kind of benefit that can last. Financial tools do not need to entertain me; they need to reduce avoidable uncertainty.
I would keep it installed for a person who checks the card several times during a normal month, especially someone who wants transaction activity close at hand without mixing it into a larger banking application. The app also makes sense for people who prefer a dedicated tool for one account instead of using a mobile browser and signing in through a general service page.
On the other hand, I would not keep it out of habit if the card is rarely used. An app that exists only for an occasional balance check has to justify its space against the convenience of opening a website when necessary. This is where the product’s focused design cuts both ways: it is pleasantly simple when needed, but it has little extra value when the underlying card is inactive.
How it compares with ordinary alternatives
Compared with checking the Way2Go Card through a browser, a dedicated app is usually more natural for repeated mobile checks. I can treat it like a purpose-built account tool rather than navigate through a website each time. The advantage is strongest for people who check the balance while away from home or who prefer keeping card activity separate from other browsing.
Compared with a full bank app, the choice is less straightforward. A bank app is better when I need one place for multiple accounts, transfers, deposits, statements, or broader money management. Go Program Way2Go Card is better when the Way2Go Card itself is the center of attention and extra financial features would only slow me down.
Compared with a budgeting app, the difference is even sharper. Budgeting software helps me decide where money should go across categories and time periods. This app helps me observe the balance and activity associated with the card. I would use both only if I wanted detailed planning alongside direct card monitoring; I would not expect one to replace the other.
That comparison also explains why the average rating of 3.5 matters to me. It suggests a mixed experience rather than a universal recommendation. The app can be exactly right for its intended cardholder and still disappoint someone expecting a polished, all-purpose finance suite. I would judge it by the narrow job it is meant to perform.
Maintenance: light, but not invisible
The maintenance burden is relatively modest because the app has a limited purpose. I do not need to build categories, maintain a budget, or enter every purchase manually just to see the card’s current position. Once it is part of my routine, the main work is remembering to check it at sensible moments and keeping my device’s operating system compatible.
That simplicity does not mean I can ignore it completely. Financial information deserves more care than a casual utility. I would avoid treating a displayed balance as permission to spend without thinking, particularly when a transaction may not yet be reflected exactly as expected. I would also make a habit of reviewing activity rather than looking only at the largest number on the screen.
The current version, 3.3.5, is the one I would use when installing today, and the minimum operating system requirement is version 10. For most compatible phones that should not be an unusual barrier, but it is still worth checking before assuming the app will work on an older device. This is a small practical detail, yet it matters for anyone relying on an older phone as their primary financial device.
There is also a human maintenance task that no interface can eliminate: deciding what to do when a transaction looks wrong. The best workflow is to take a screenshot or note the relevant details for personal reference, compare the entry with receipts, and use the official support route associated with the card if the issue remains. The app is valuable for early detection, but it is not the final step in a dispute.
Where fatigue can set in
The biggest source of fatigue is repetition without expansion. Once I have learned where to find the balance and transaction activity, there may be little else to discover. That is acceptable for a utility, but it means the app must remain dependable and quick. If I expect new tools, richer analysis, or a more complete financial picture over time, I may start seeing the narrow scope as a weakness.
Another possible frustration is using the app when I need context beyond the card account. A balance can tell me what is available, but it does not automatically answer whether I can afford all of next week’s obligations. Transaction activity can show what happened, but it does not necessarily turn those entries into a plan. I have to supply that wider context myself.
People who dislike checking financial apps repeatedly may also find the product less rewarding. Its value is tied to a recurring habit, not a single setup session. I would not recommend it to someone who wants a tool that actively organizes every aspect of their finances. A broader banking or budgeting option would be a better fit for that expectation.
There is a subtler trade-off in dedicated finance apps as well: separation is useful, but it can create another place to remember. If I already monitor several accounts, adding a card-specific app may fragment my routine. In that situation, the focused experience is worthwhile only if the Way2Go Card is important enough that direct access saves more time than the extra app adds.
Who should install it, and who should skip it
I would recommend Go Program Way2Go Card to an active Way2Go Card holder who wants a straightforward mobile way to watch available funds and recent transactions. It is also a sensible choice for someone who values a dedicated card companion and does not need a full financial dashboard. The free price removes the cost barrier, while the Everyone age classification makes it broadly approachable.
I would suggest skipping it if the Way2Go Card is rarely used, if all financial activity is already handled comfortably inside another service, or if the main goal is detailed budgeting. It is also not the right first choice for someone looking for investment tracking, multi-account planning, or advanced spending analysis. Those needs belong to a different class of app.
For a shared household, I would be more careful about assuming that one person’s checking routine solves everyone’s information needs. The app may help the cardholder monitor activity, but household budgeting still requires a separate agreement about records, upcoming bills, and spending limits. Its usefulness is strongest when expectations stay aligned with the card account itself.
My long-term verdict
After the first-week convenience fades, this app earns lasting space only through a simple promise: when I need to know what is happening with my Way2Go Card, it gives me a direct place to look. That is a modest promise, but it can be genuinely useful when the card is part of regular life.
I like the focused role more than I would like an overloaded finance app trying to do everything. The ability to check available balance and transaction activity supports practical routines before and after spending, and those routines can prevent mistakes. The trade-off is that the app offers little reason to open it when the card is inactive or when I need broader money management.
My recommendation is therefore conditional but positive: keep it if you use the Way2Go Card regularly and value direct monitoring; choose a browser, bank app, or budgeting tool instead if your needs extend beyond that account. With over a million installs, it has clearly found a real audience, but its 3.5 average rating is a useful reminder to approach it as a specialized utility rather than a flawless financial hub.
In my experience, its lasting value comes from habit, not novelty. A quick check before spending, a review after activity, and a careful response to anything unfamiliar are enough to make the app worthwhile. If that routine matches the way you use the card, Go Program Way2Go Card is a practical companion. If you want the app to organize your entire financial life, it is better to look elsewhere.
FAQ
What is the Go Program Way2Go Card used for?
The Go Program Way2Go Card is a prepaid benefit card commonly used by participating government agencies to distribute payments such as unemployment benefits, child support, or other public assistance. It is not a standard bank account or credit card. Your exact card features, payment schedule, and permitted uses depend on the agency that issued it and the terms attached to your specific program.
What can I do with the Go Program Way2Go Card mobile app?
The Way2Go Card app is designed to help eligible cardholders manage their account from a mobile device. Depending on your state or program, you may be able to check your balance, review transactions, locate ATMs, view payment information, and manage account settings. Available features can vary, so some users may see different options after signing in.
How do I activate my Way2Go Card and register it in the app?
Before using the card, you generally need to activate it through the official Way2Go Card service and create or access your cardholder account. The process may require your card number, security information, personal identification details, and a verification code. Use only the official app or website supplied by your issuing agency, and never share your PIN or login credentials with anyone.
Are there fees for using the Go Program Way2Go Card?
Fees depend on the card program, state, and type of transaction. Some services may be free, while others can involve charges for out-of-network ATM withdrawals, replacement cards, expedited services, balance inquiries, or certain transfers. Review the fee schedule provided with your card and check the app or official cardholder website before making withdrawals or selecting optional services.
What should I do if my Way2Go Card is lost, stolen, declined, or shows an unfamiliar transaction?
If your card is lost, stolen, declined unexpectedly, or displays a transaction you do not recognize, contact Way2Go Card customer service immediately using the official phone number printed on the card or listed in the app. Lock or report the card if that option is available, change your login credentials when appropriate, and keep records of disputed transactions and support reference numbers.


